Housing Market Update
Awni & Chantell Abbas
REALTORS
Awntel Property Advisors
Equal Housing Opportunity
“AWNTELL IT LIKE IT IS” SHOW
7 STAR SERVICE

Find your perfect neighborhood

See ALL the homes that qualify!

Get an INSTANT home valuation

Check on the local real estate market
Housing Market Update
Awni & Chantell Abbas
REALTORS
Awntel Property Advisors
Equal Housing Opportunity
“AWNTELL IT LIKE IT IS” SHOW
7 STAR SERVICE
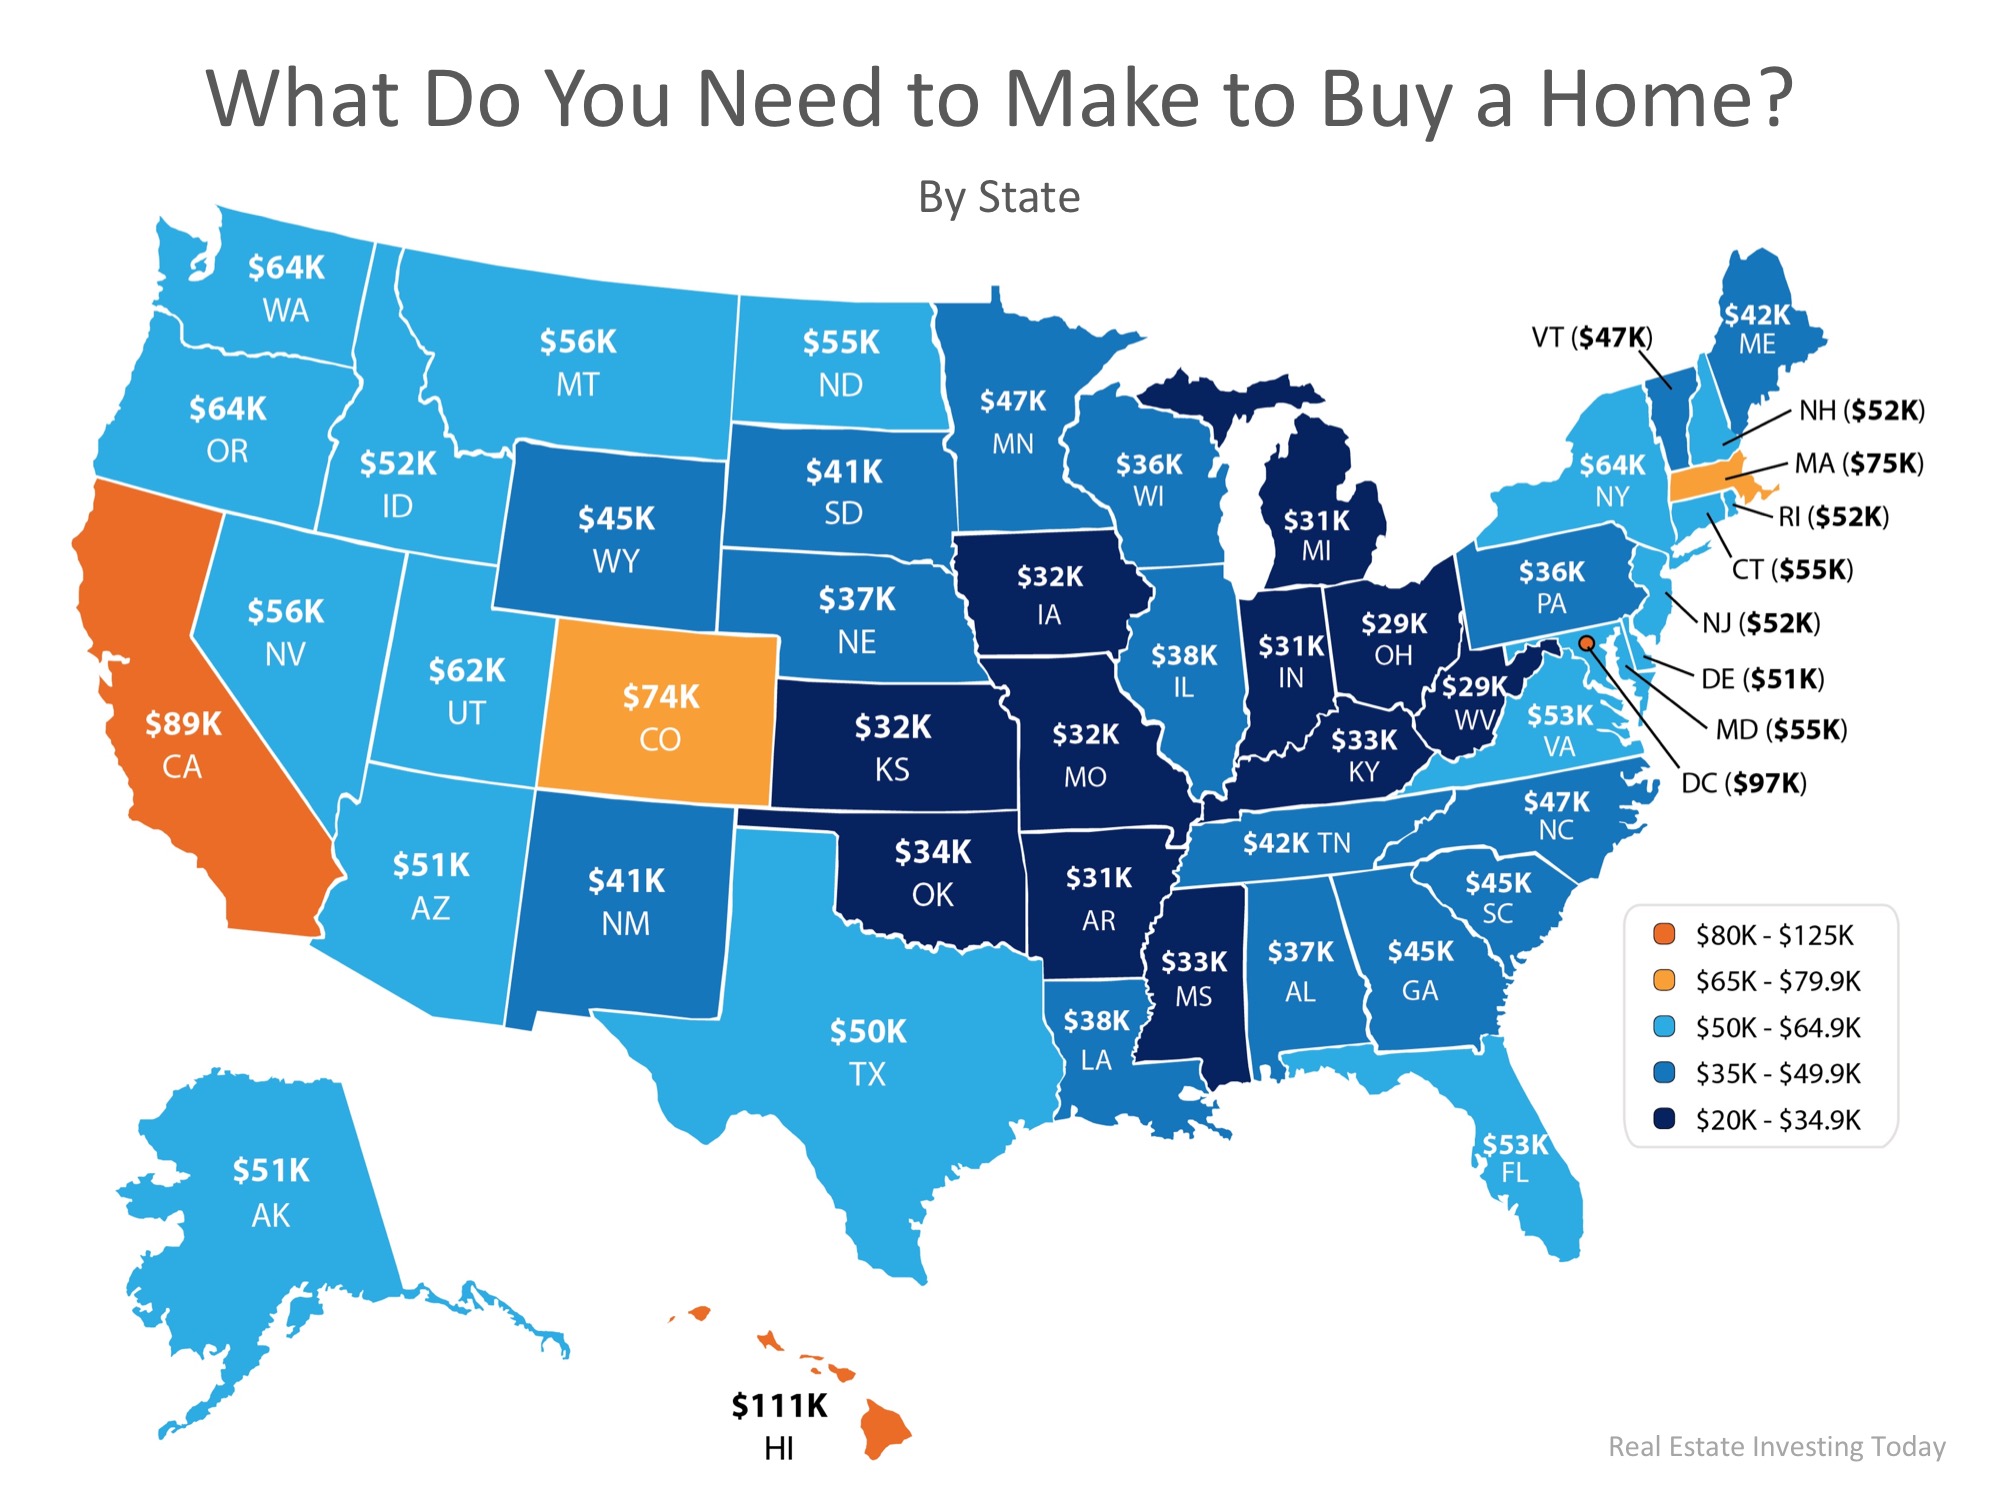
It’s no mystery that cost of living varies drastically depending on where you live, so a new study by GOBankingRates set out to find out what minimum salary you would need to make in order to buy a median-priced home in each of the 50 states, and Washington, D.C.
States in the Midwest came out on top as most affordable, requiring the smallest salaries in order to buy a median-priced home. States with large metropolitan areas saw a bump in the average salary needed to buy with California, Washington, D.C., and Hawaii edging out all others with the highest salaries required.
Below is a map with the full results of the study:
GoBankingRates gave this advice to anyone considering a home purchase,
“Before you buy a home, it’s important to find out if you can afford the monthly mortgage payment. To do this, some financial experts recommend your housing costs — primarily your mortgage payments — shouldn’t consume more than 30 percent of your monthly income.”
As we recently reported, research from Zillow shows that historically, Americans had spent 21% of their income on owning a median-priced home. The latest data from the fourth quarter of 2017 shows that the percentage of income needed today is only 15.7%!
If you are considering buying a home, whether it’s your first time or your fifth time, let’s get together to evaluate your ability to do so in today’s market!
Housing Market Update
Awni & Chantell Abbas
REALTORS
Awntel Property Advisors
Equal Housing Opportunity
“AWNTELL IT LIKE IT IS” SHOW
7 STAR SERVICE

When it comes time to sell your home, you know you’ll need to spend some time cleaning the carpets, decluttering, and landscaping for maximum curb appeal. But there’s another key task to add to your to-do list: checking in with your local government to be sure it has accurate information about your home.
No matter the type or size of your home or where it is, your local municipality has documentation on it. Both the building department and the town assessor will have a record about your home. But those records may not match your home’s reality and any issues you don’t resolve could hold up your sale or even kill the deal altogether.
Before listing, a seller should go to the town hall and check their property records. Most of the time, remedying issues like open permits or misinformation on a property is a quick fix. It’s better to get ahead of it than to have to react to a buyer’s concerns and jeopardize your deal.
If it’s a bigger issue, it’s better to hold off on listing your home for sale until you have resolved it. Getting your assessment down can impact your taxes, and that will be great news to your potential buyers.
-Awntel
For a FREE property search go to http://cenphxliving.com
For a FREE home value report go to http://cenphxhomevalues.com
For my FREE real estate guide book, go to http://phxrealestateinsider.com
If you liked this video, please "Like" Forward Share or Subscribe to our Channel!
THANK YOU!
-Awni & Chantell Abbas
Awntel Property Advisors
5134 N Central Ave #101
Phoenix, Az 85012
Office: 602-472-3489
Mobile: Call or text 480-788-4118
“AWNTELL IT LIKE IT IS” SHOW
7 STAR SERVICE

Over the next five years, home prices are expected to appreciate, on average, by 3.6% per year and to grow by 18.2% cumulatively, according to Pulsenomics’ most recent Home Price Expectation Survey.
As an example, let’s assume a young couple purchased and closed on a $250,000 home this January. If we only look at the projected increase in the price of that home, how much equity will they earn over the next 5 years?
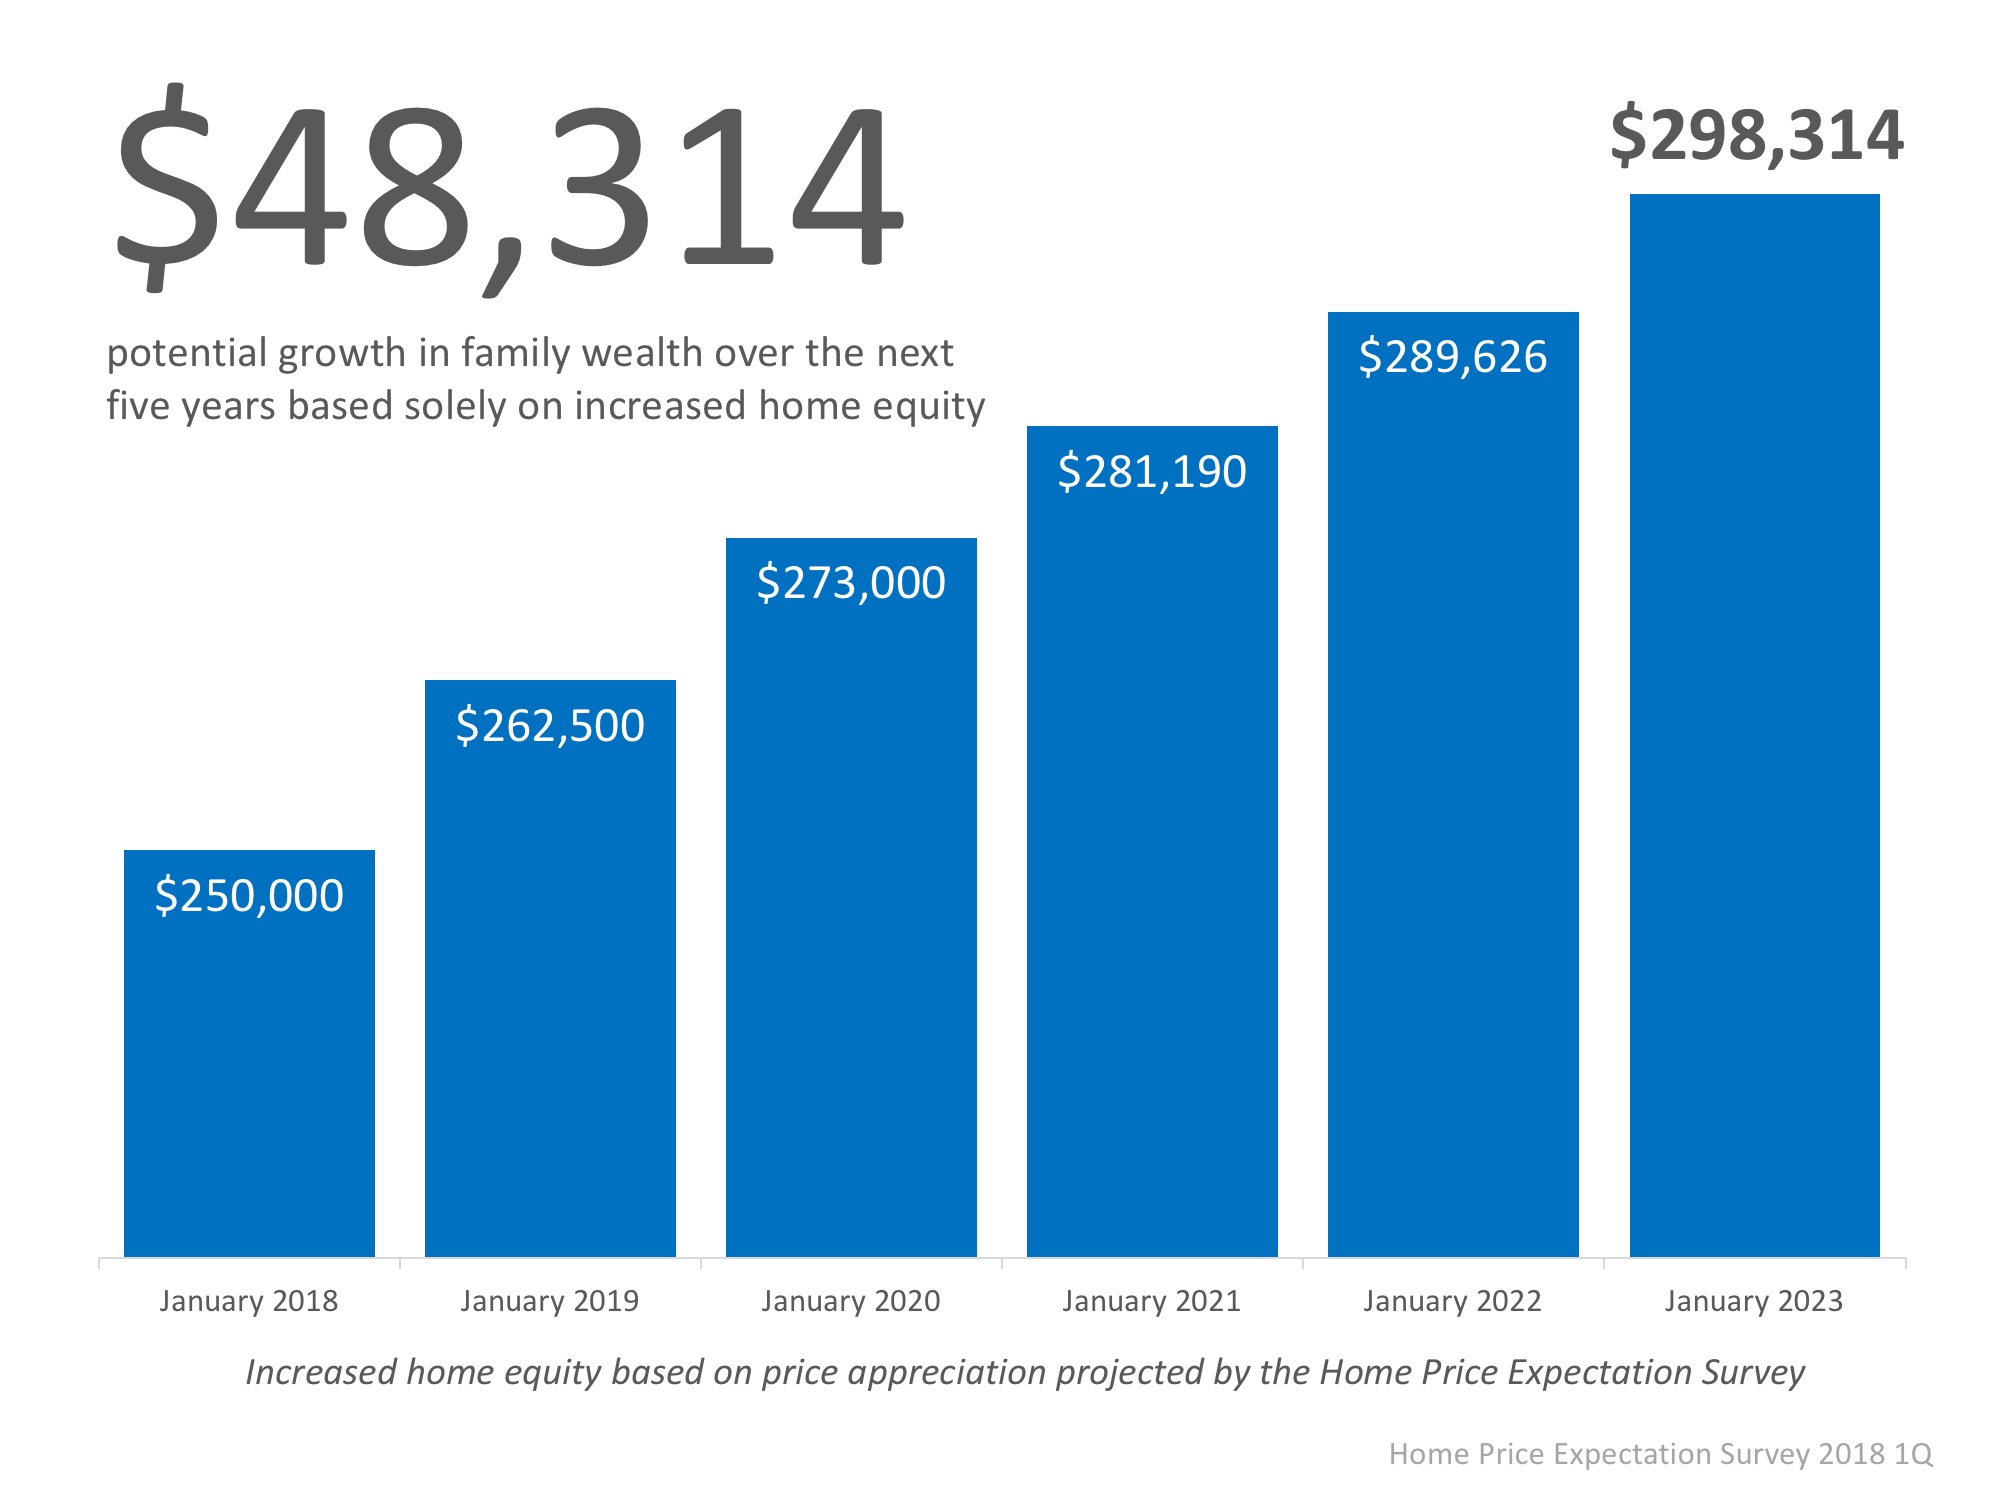
Since the experts predict that home prices will increase by 5.0% in 2018, the young homeowners will have gained $12,500 in equity in just one year.
Over a five-year period, their equity will increase by over $48,000! This figure does not even take into account their monthly principal mortgage payments. In many cases, home equity is one of the largest portions of a family’s overall net worth.
Not only is homeownership something to be proud of, but it also offers you and your family the ability to build equity you can borrow against in the future. If you are ready and willing to buy, find out if you are able to today!
Housing Market Update
Awni & Chantell Abbas
REALTORS
Awntel Property Advisors
Equal Housing Opportunity
“AWNTELL IT LIKE IT IS” SHOW
7 STAR SERVICE

In many markets across the country, the number of buyers searching for their dream homes greatly outnumbers the number of homes for sale. This has led to a competitive marketplace where buyers often need to stand out. One way to show you are serious about buying your dream home is to get pre-qualified or pre-approved for a mortgage before starting your search.
Even if you are in a market that is not as competitive, understanding your budget will give you the confidence of knowing if your dream home is within your reach.
Freddie Mac lays out the advantages of pre-approval in the ‘My Home’ section of their website:
“It’s highly recommended that you work with your lender to get pre-approved before you begin house hunting. Pre-approval will tell you how much home you can afford and can help you move faster, and with greater confidence, in competitive markets.”
One of the many advantages of working with a local real estate professional is that many have relationships with lenders who will be able to help you with this process. Once you have selected a lender, you will need to fill out their loan application and provide them with important information regarding “your credit, debt, work history, down payment and residential history.”
Freddie Mac describes the ‘4 Cs’ that help determine the amount you will be qualified to borrow:
Getting pre-approved is one of many steps that will show home sellers that you are serious about buying, and it often helps speed up the process once your offer has been accepted.
Many potential home buyers overestimate the down payment and credit scores needed to qualify for a mortgage today. If you are ready and willing to buy, you may be pleasantly surprised at your ability to do so.
Housing Market Update
Awni & Chantell Abbas
REALTORS
Awntel Property Advisors
Equal Housing Opportunity
“AWNTELL IT LIKE IT IS” SHOW
7 STAR SERVICE

There is no doubt that the price of a home in most regions of the country is greater now than at any time in history. However, when we look at the cost of a home, it is cheaper to own today than it has been historically.
The price of a home is the dollar amount you and the seller agree to at the time of purchase. The cost of a home is the monthly expense you pay for your mortgage payment.
To accurately compare costs in different time periods, we must look at home prices, mortgage rates, and wages during each period. Home prices were less expensive years ago, but paychecks were also smaller and mortgage rates were much higher (the average mortgage interest rate in 1988 was 10.34%).
The best way to measure the COST of a home is to determine what percentage of income is necessary to buy a home at the time. That would take into account the price of the home, the mortgage interest rate and wages at the time.
Zillow just released research that examined home costs using this formula. The research compares the historic percentage of income necessary to afford a mortgage to the percentage needed today. It also revealed the cost if mortgage rates continue to rise as experts are predicting. Here is a graph of their findings*:
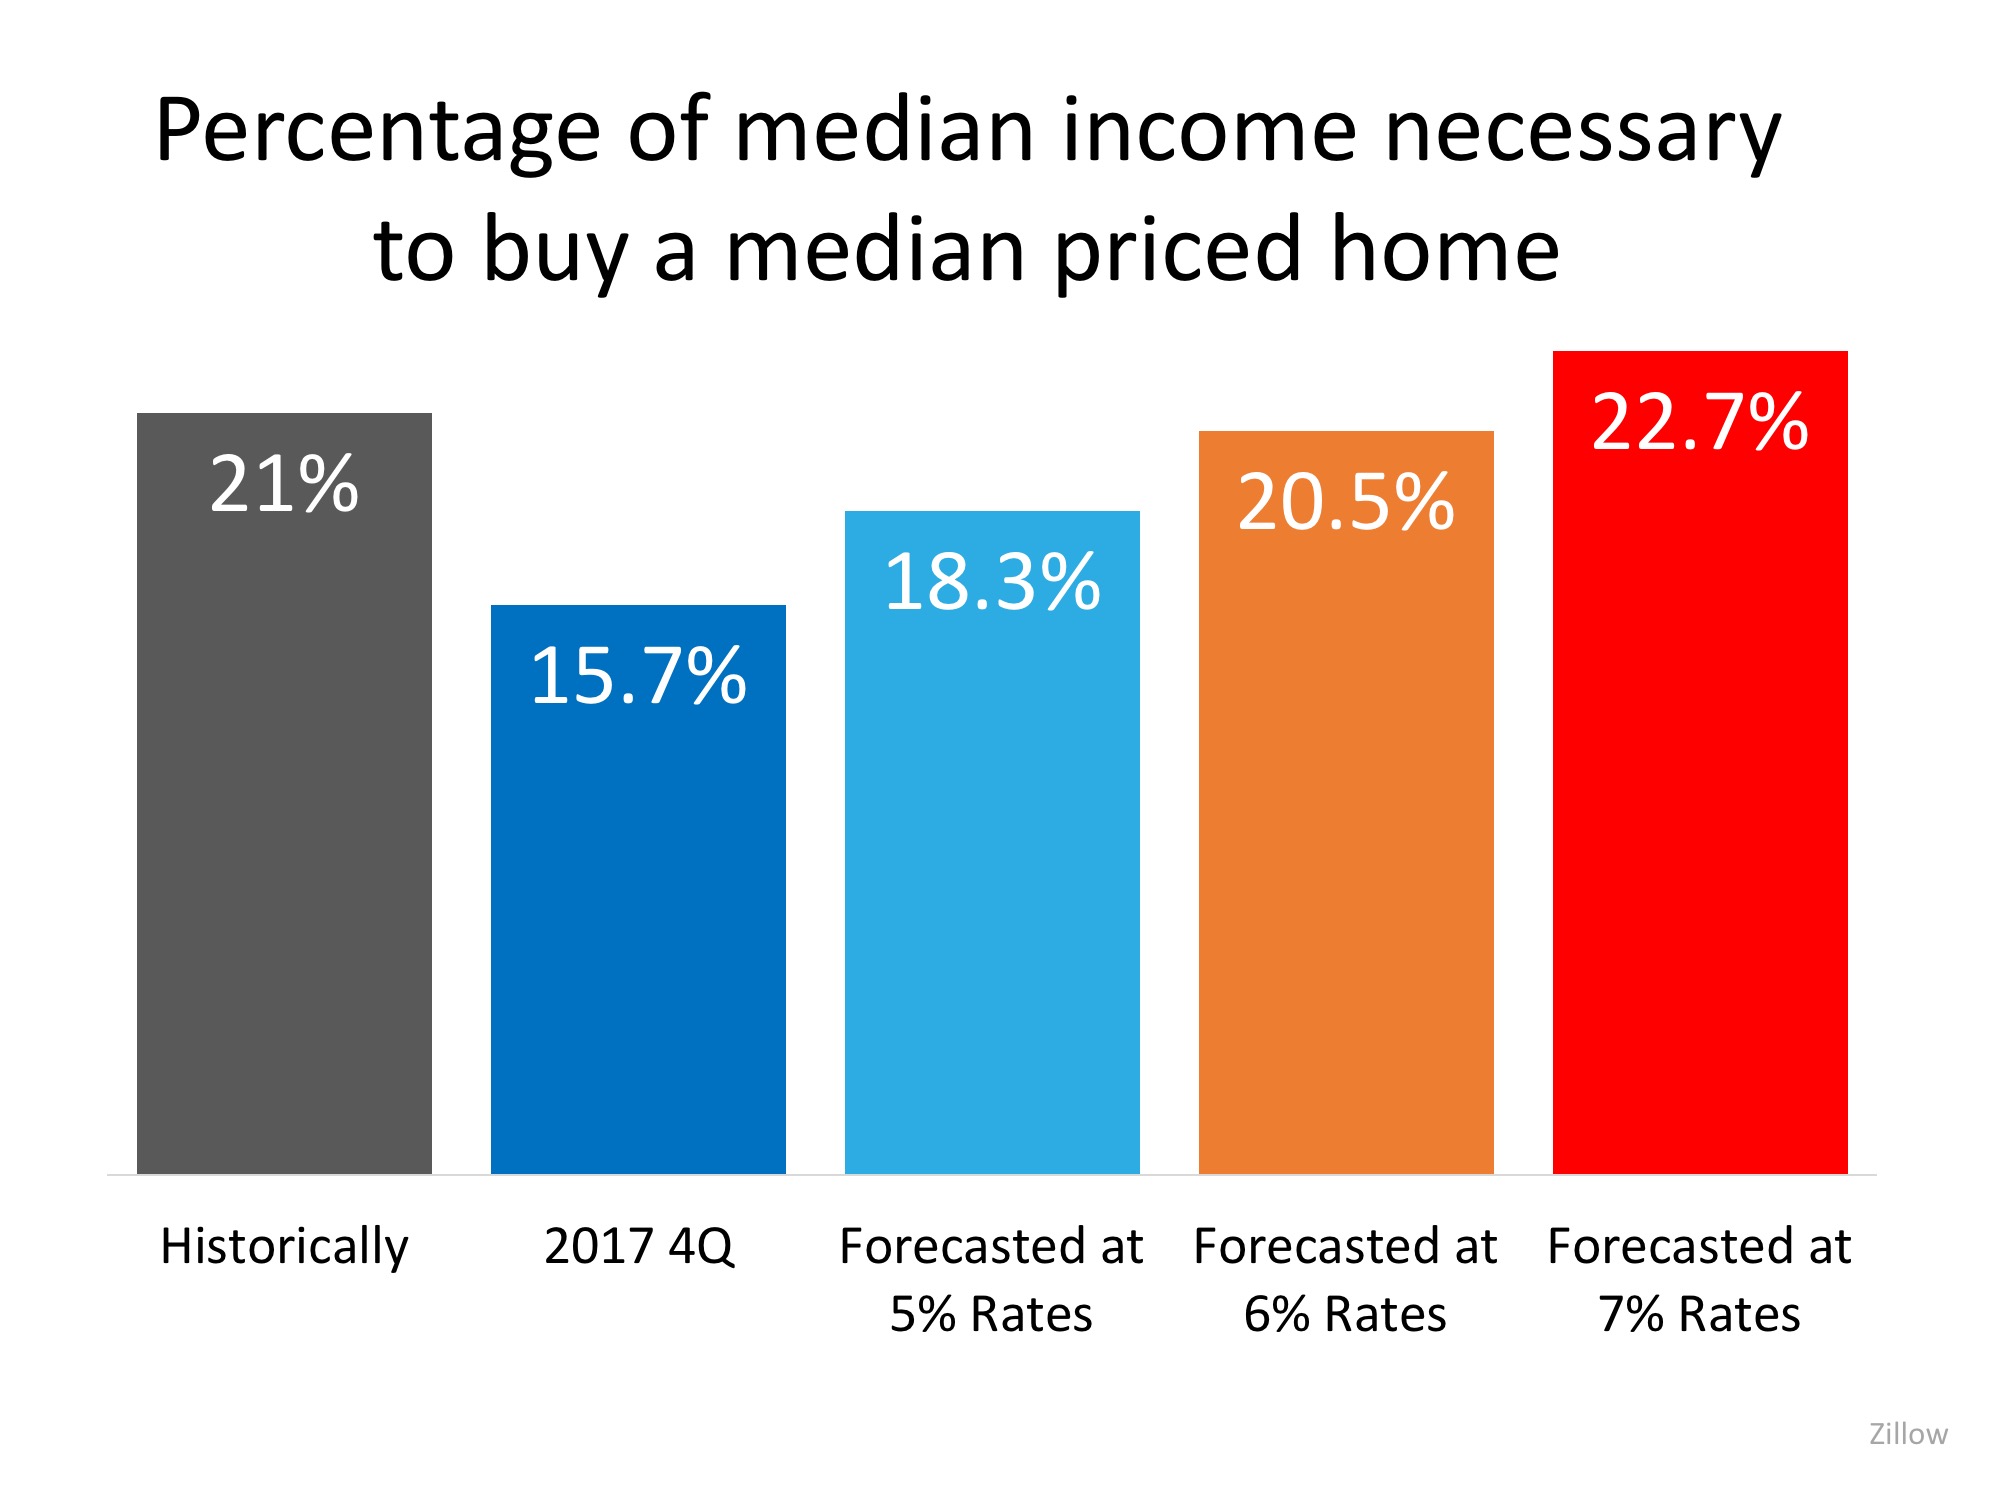
Rates would need to jump to 7% in order for the percentage of necessary income to be greater than historic norms.
Whether you are a homeowner considering selling your current house and moving up to the home of your dreams, or a first-time buyer trying to purchase your first home, it’s a great time to move forward.
*Assumptions in the Zillow report: Buyer puts 20% down, takes out a conforming, 30-year fixed-rate mortgage at rates prevailing at the time, earns the median household income, and is buying a median-valued home.