Phoenix Real Estate and Community News

April 11, 2018

Mortgage Interest Rates Have Begun to Level Off

Mortgage Interest Rates Have Begun to Level Off | MyKCM

Whether you are a buyer searching for your first home, or a homeowner looking to move up to your next home, you should pay attention to where mortgage interest rates are heading.

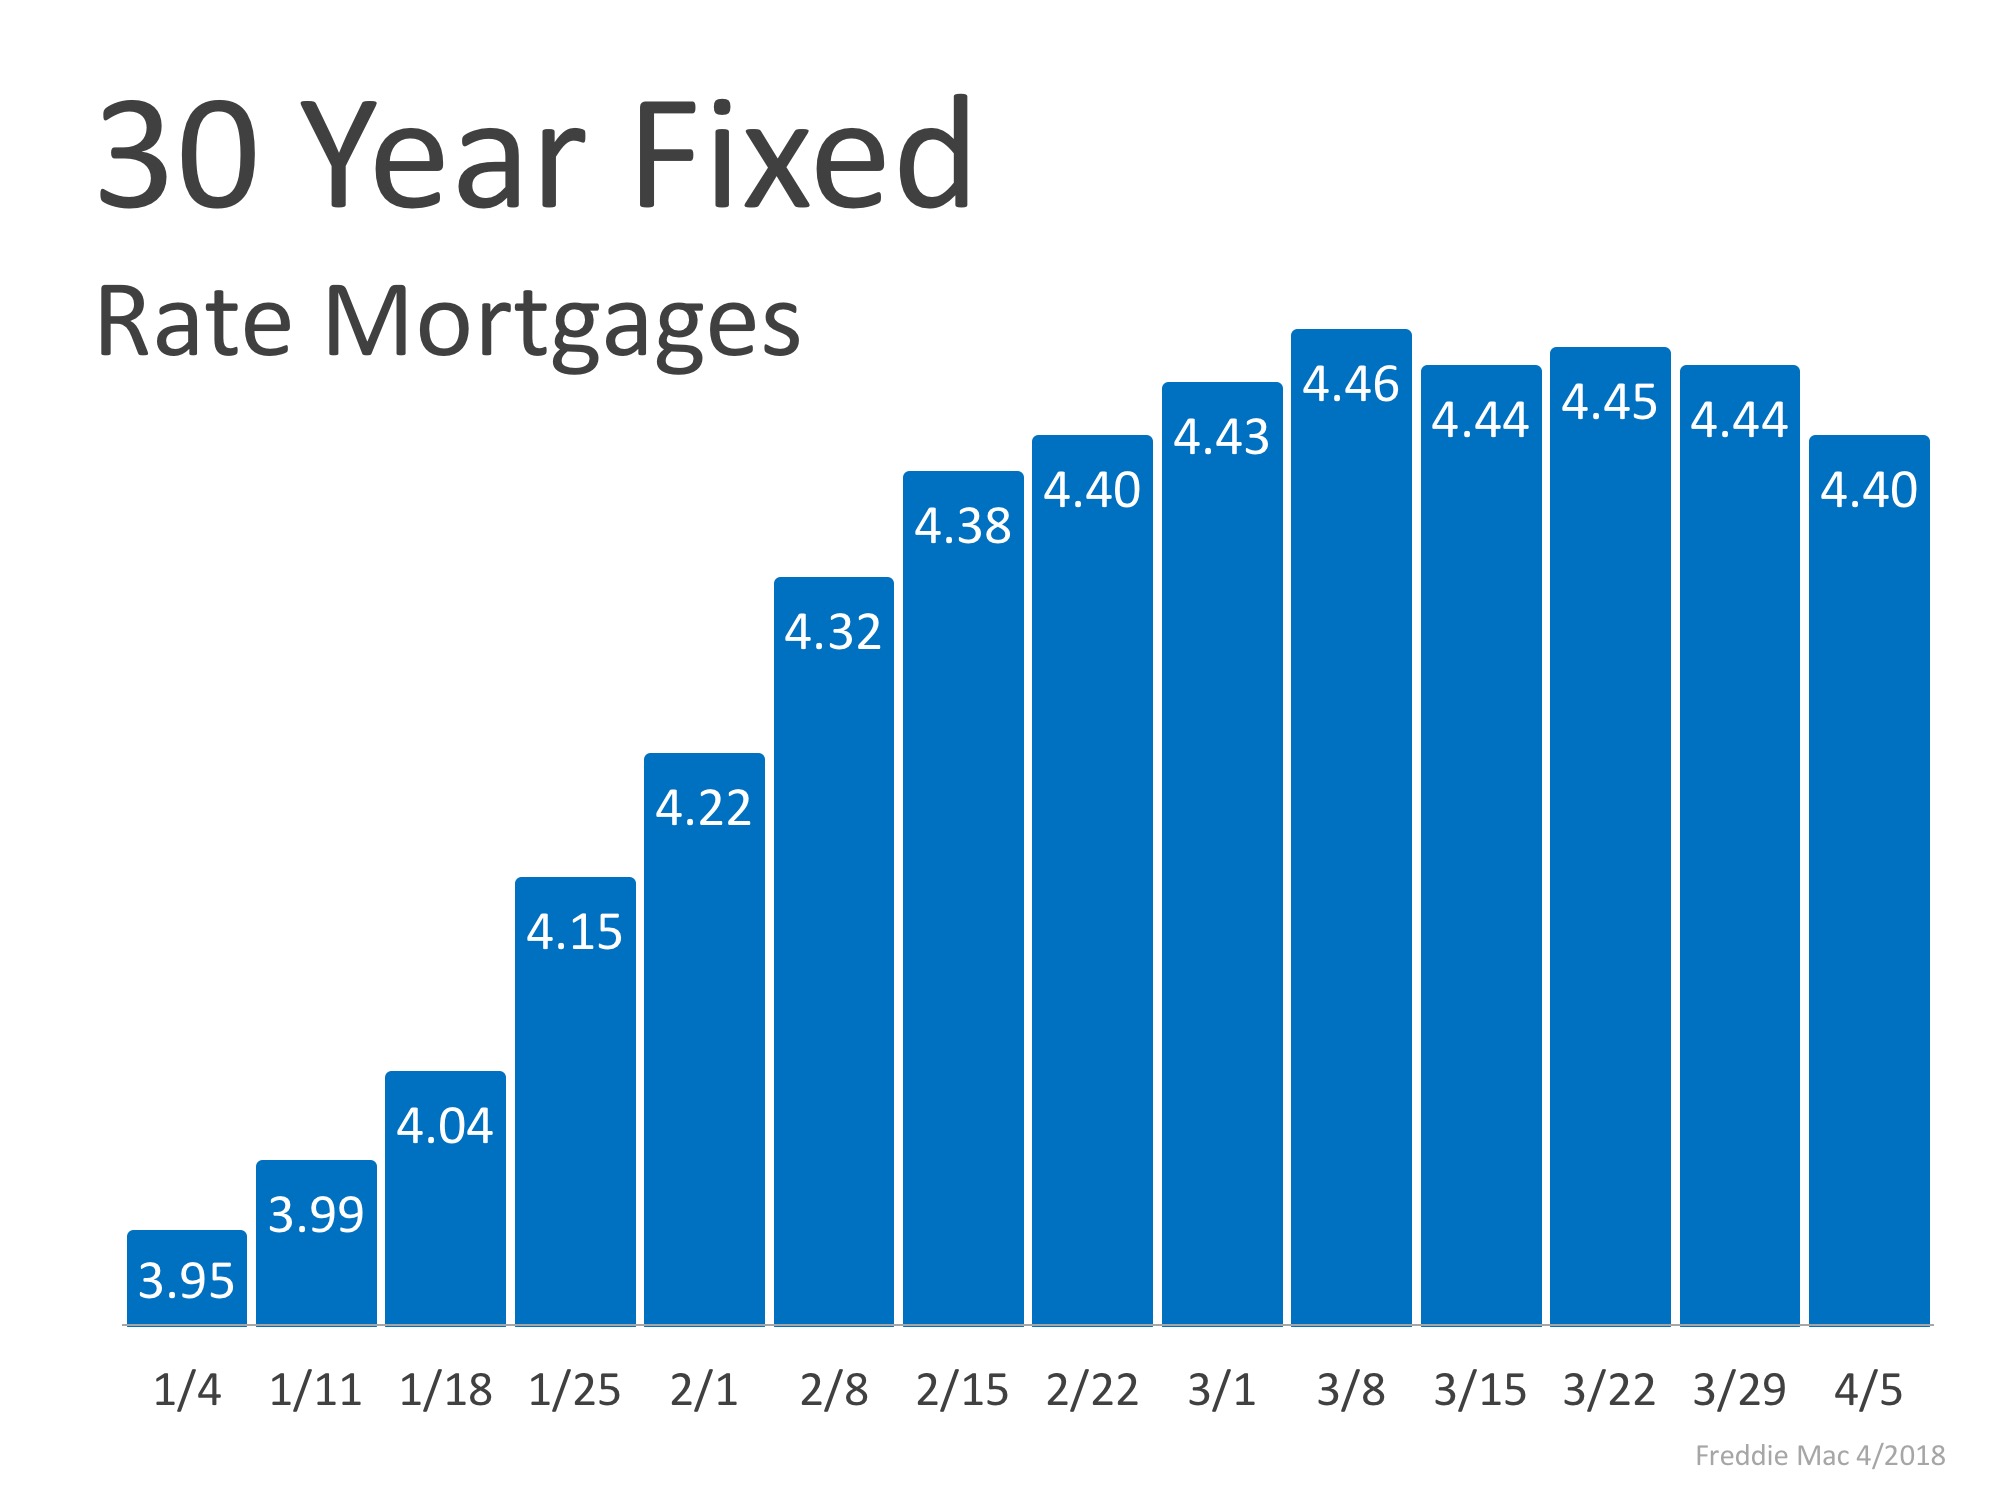
Over the course of 2018, according to Freddie Mac’s Primary Mortgage Market Survey, rates have increased from 3.95% in the first week of January to 4.40% in the first week of April.

At first glance, the difference between these numbers in such a short amount of time could be concerning, but if we look at the graph below, we’ll see that rates have already started to level off and return to the mark set in February.
Mortgage Interest Rates Have Begun to Level Off | MyKCM

This is great news for anyone looking to buy a home this spring! The spring is always one of the busiest seasons for home buying, and with rates increasing even more, buyers have come off the fence to lock in great rates! This is still great advice as the experts believe that rates will continue to rise throughout the year.

Every month, Freddie Mac, Fannie Mae, the Mortgage Bankers Association and the National Association of Realtors release their projections for where they believe mortgage rates will be in the coming months. If we take the average of what each of the four organizations is predicting for the second quarter, rates are expected to rise to about 4.48% by June.

That average climbs to 4.73% by the end of this year.

So, what does this mean?

Waiting until the end of the year to buy, with rates still projected to increase, will end up costing you more money on your monthly mortgage payment. For every $250,000 you need to borrow to purchase your dream home, you will spend $49.21 more per month, $590.52 per year, and over $17,700 by the end of your 30-year mortgage.

And that’s just the impact of your interest rate going up!

Bottom Line

If you are ready and willing to purchase a home, find out if you’re able to. Let’s get together to evaluate your needs and help you with next steps!
Posted in Buying a Home
April 10, 2018

How To Compete Againts Cash Home Buyers

Buyers making a cash offer on a house are active in many markets, and they can strike fear in new buyers who are bidding on a home. Cash home buyers can perform and close quickly and provide sellers with a sense of comfort.


But does this mean a solid buyer putting down 20 percent or more shouldn’t attempt to compete with cash home buyers? Absolutely not.


What if you can’t make a cash offer on a house?


The truth is, a buyer getting a mortgage can still compete against cash home buyers and win. 


Structure your offer to show that you’re ready to roll.


Watch the video for some strategies that can help you win! 

-Awntel


For a FREE property search go to http://cenphxliving.com


For a FREE home value report go to http://cenphxhomevalues.com


For my FREE real estate guide book, go to http://phxrealestateinsider.com


If you liked this video, please "Like" Forward Share or Subscribe to our Channel! 


THANK YOU!

-Awni & Chantell Abbas

Awntel Property Advisors 

5134 N Central Ave #101

Phoenix, Az 85012

Office: 602-472-3489

Mobile: Call or text 480-788-4118

http://cenphxliving.com

“AWNTELL IT LIKE IT IS” SHOW

7 STAR SERVICE


Posted in Buying a Home
April 10, 2018

What Is Private Mortgage Insurance (PMI)?

What Is Private Mortgage Insurance (PMI)? | MyKCM

When it comes to buying a home, whether it is your first time or your fifth, it is always important to know all the facts. With the large number of mortgage programs available that allow buyers to purchase homes with down payments below 20%, you can never have too much information about Private Mortgage Insurance (PMI).

What is PMI?

Freddie Mac defines PMI as:

“An insurance policy that protects the lender if you are unable to pay your mortgage. It’s a monthly fee, rolled into your mortgage payment, that is required for all conforming, conventional loans that have down payments less than 20%.

Once you’ve built equity of 20% in your home, you can cancel your PMI and remove that expense from your mortgage payment.”

As the borrower, you pay the monthly premiums for the insurance policy, and the lender is the beneficiary. Freddie Mac goes on to explain that:

“The cost of PMI varies based on your loan-to-value ratio – the amount you owe on your mortgage compared to its value – and credit score, but you can expect to pay between $30 and $70 per month for every $100,000 borrowed.” 

According to the National Association of Realtors, the average down payment for all buyers last year was 10%. For first-time buyers, that number dropped to 5%, while repeat buyers put down 14% (no doubt aided by the sale of their homes). This just goes to show that for a large number of buyers last year, PMI did not stop them from buying their dream homes.

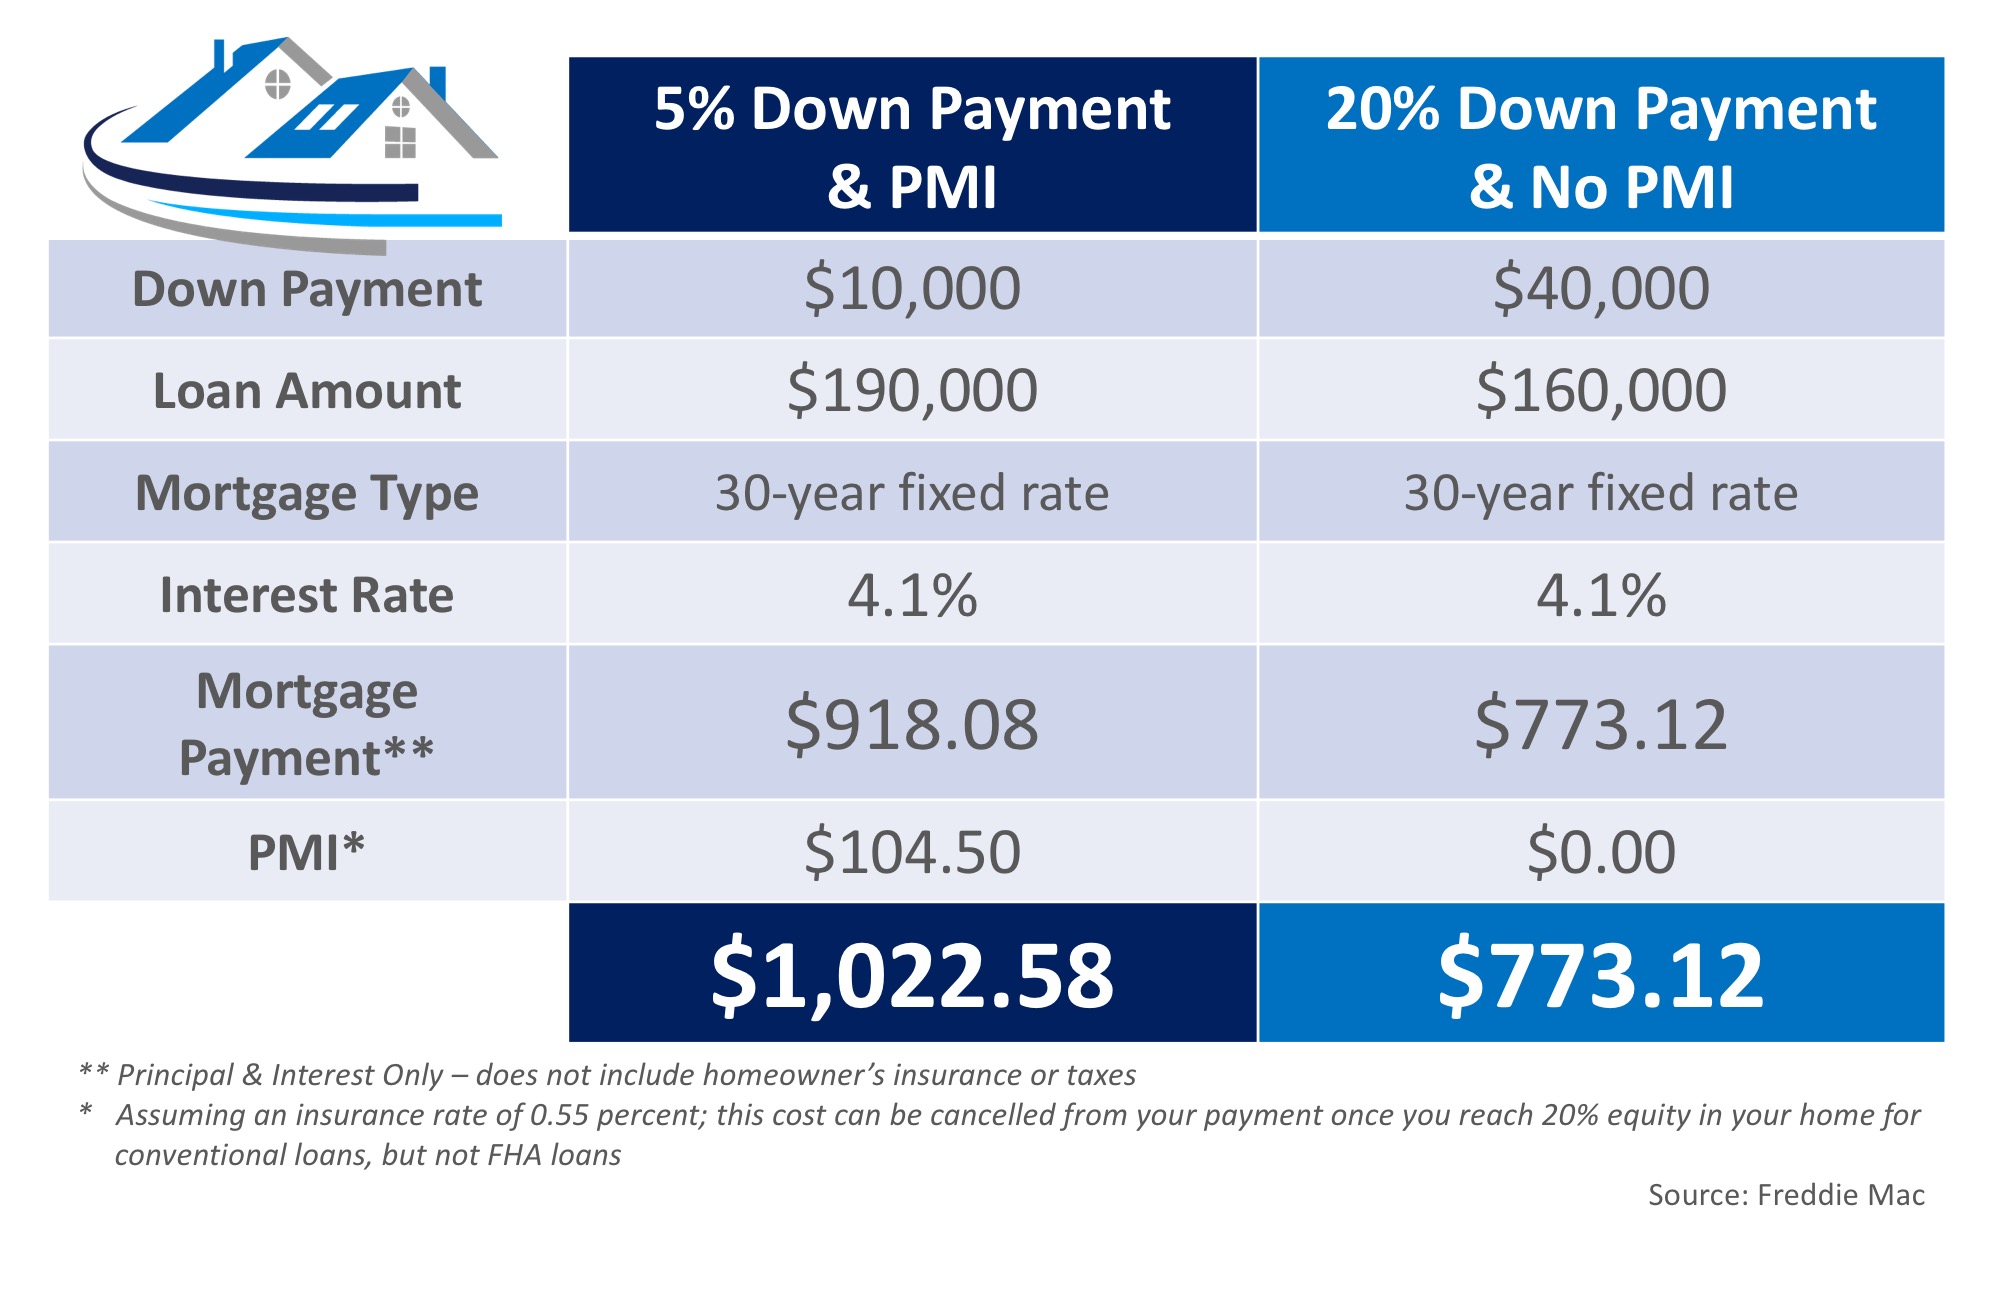
Here’s an example of the cost of a mortgage on a $200,000 home with a 5% down payment & PMI, compared to a 20% down payment without PMI:

What Is Private Mortgage Insurance (PMI)? | MyKCM

The larger the down payment you can make, the lower your monthly housing cost will be, but Freddie Mac urges you to remember:

“It’s no doubt an added cost, but it’s enabling you to buy now and begin building equity versus waiting 5 to 10 years to build enough savings for a 20% down payment.”

Bottom Line

If you have questions about whether you should buy now or wait until you’ve saved a larger down payment, let’s get together to discuss our market’s conditions and help you make the best decision for you and your family.

Posted in Buying a Home
April 9, 2018

US Housing Market Still In ‘Buy Territory’!

US Housing Market Still In ‘Buy Territory’! | MyKCM

According to the Beracha, Hardin & Johnson Buy vs. Rent (BH&J) Index, the U.S. housing market has continued to move deeper into buy territory, supporting the belief that housing markets across the country remain a sound investment.

The BH&J Index is a quarterly report that attempts to answer the question:

In today’s housing market, is it better to rent or buy a home?

The index examines the entire US housing market and then isolates 23 major cities for comparison. The researchers “measure the relationship between purchasing property and building wealth through a buildup in equity versus renting a comparable property and investing in a portfolio of stocks and bonds.” 

While 13 of the 23 metropolitan markets examined moved further into buy territory, markets like Dallas, Denver, and Houston are currently deep into rent territory. Due to a lack of inventory, the home prices in these areas have increased by 6.7%6.3%, and 5.3%  respectively from a year ago.

According to Eli Beracha, Ph.D., Co-Creator of the index, home prices will begin to return to more normal levels.

Our data indicates that prices are above their 40-year trend but not significantly so as they were in 2007. Rather than a crash, I anticipate slower growth in prices accompanied by longer marketing times for sellers and increasing inventories, which should bring prices back in conjunction with their 40-year trend.”

Bottom Line

The majority of the country is strongly in buy territory. Buying a home makes sense socially and financially, as rents are predicted to increase substantially in the next year. Protect yourself from rising rents by locking in your housing cost with a mortgage payment now. 

To Find Out More About the Study: The BH&J Index and other FAU real estate activities are sponsored by Investments Limited of Boca Raton. The BH&J Index is published quarterly and is available online at http://business.fau.edu/buyvsrent.

Posted in Buying a Home
April 6, 2018

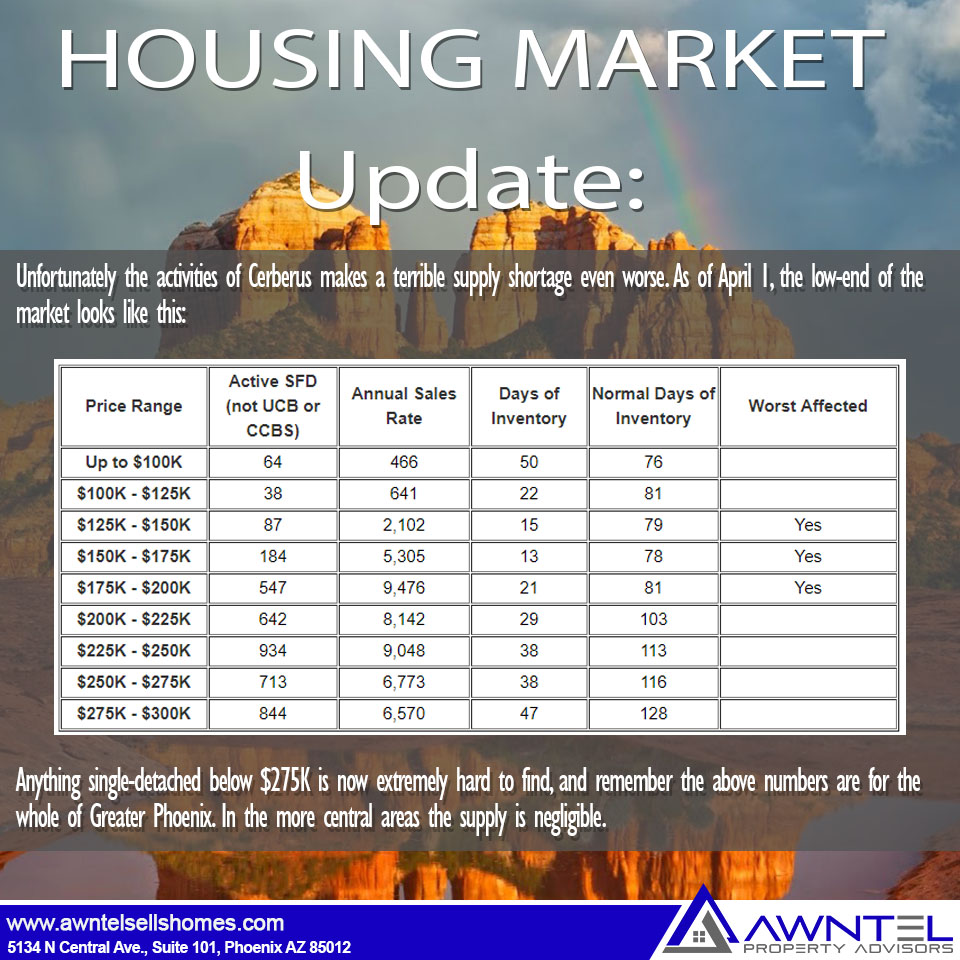
Housing Market Update

Housing Market Update
Awni & Chantell Abbas
REALTORS
Awntel Property Advisors
Equal Housing Opportunity
“AWNTELL IT LIKE IT IS” SHOW
7 STAR SERVICE

Posted in Real Estate News
April 6, 2018

VA Loans by the Numbers [INFOGRAPHIC]

VA Loans by the Numbers [INFOGRAPHIC] | MyKCM

Some Highlights:

  • Since the creation of the VA Home Loans Program, 22 million veterans have been able to achieve the American Dream of homeownership.
  • In 2017, $188 billion was loaned to veterans and their families through the program.
  • VA Purchase Loans are on the rise in 46 out of 50 states and Washington, DC.
Posted in Buying a Home
April 5, 2018

Wow, thank you Greg and Jennifer for the wonderful review!!

Wow, thank you Greg and Jennifer for the wonderful review!! We truly appreciate your business, and we’re grateful for the trust you’ve placed in us. Thank you for the privilege of your business! Our clients are the reason we stand strong!! ??????? 

Awni & Chantell Abbas

REALTORS

Awntel Property Advisors

Equal Housing Opportunity

“AWNTELL IT LIKE IT IS” SHOW

7 STAR SERVICE 

Posted in Buying a Home
April 4, 2018

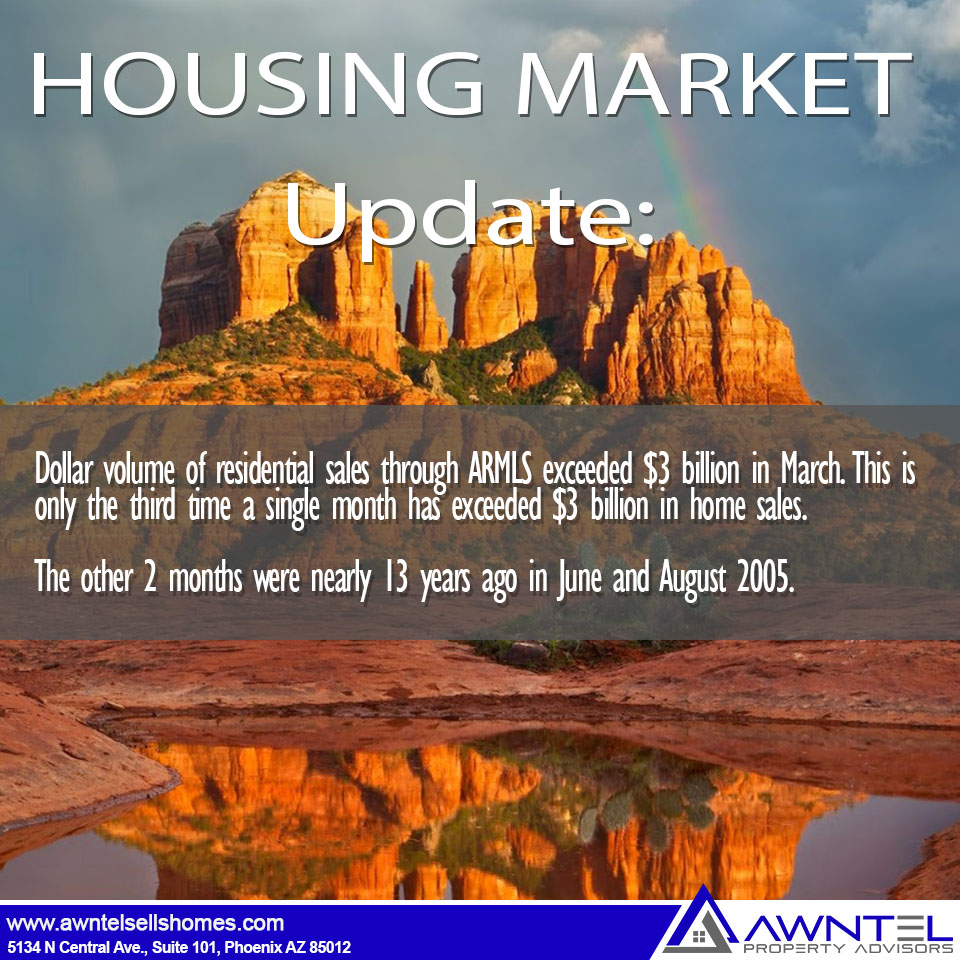
Housing Market Update

Housing Market Update
Awni & Chantell Abbas
REALTORS
Awntel Property Advisors
Equal Housing Opportunity
“AWNTELL IT LIKE IT IS” SHOW
7 STAR SERVICE

Posted in Real Estate News
April 4, 2018

Wow, Incredible buyer review! Thank you so much for your kind words, Duke and Sam

Wow, Incredible buyer review! Thank you so much for your kind words, Duke and Sam.

Awni & Chantell Abbas

REALTORS

Awntel Property Advisors

Equal Housing Opportunity

“AWNTELL IT LIKE IT IS” SHOW

7 STAR SERVICE 


Posted in Buying a Home
April 4, 2018

Boomerang Buyers: Most Qualify for Financing in 2-3 Years

Boomerang Buyers: Most Qualify for Financing in 2-3 Years | MyKCM

According to a new study from Lending Tree, Americans who have filed for bankruptcy may be able to rebuild enough credit to qualify for a home loan in as little as 2-3 years.

This is in stark contrast to the belief that many have that they need to wait 7-10 years for their bankruptcies to clear from their credit reports before attempting to apply for either a mortgage or a personal or auto loan.

The study analyzed over one million loan applications for mortgages, personal, and auto loans and compared borrowers who had a bankruptcy on their credit report vs. those who did not to find out the “Cost of Bankruptcy.”

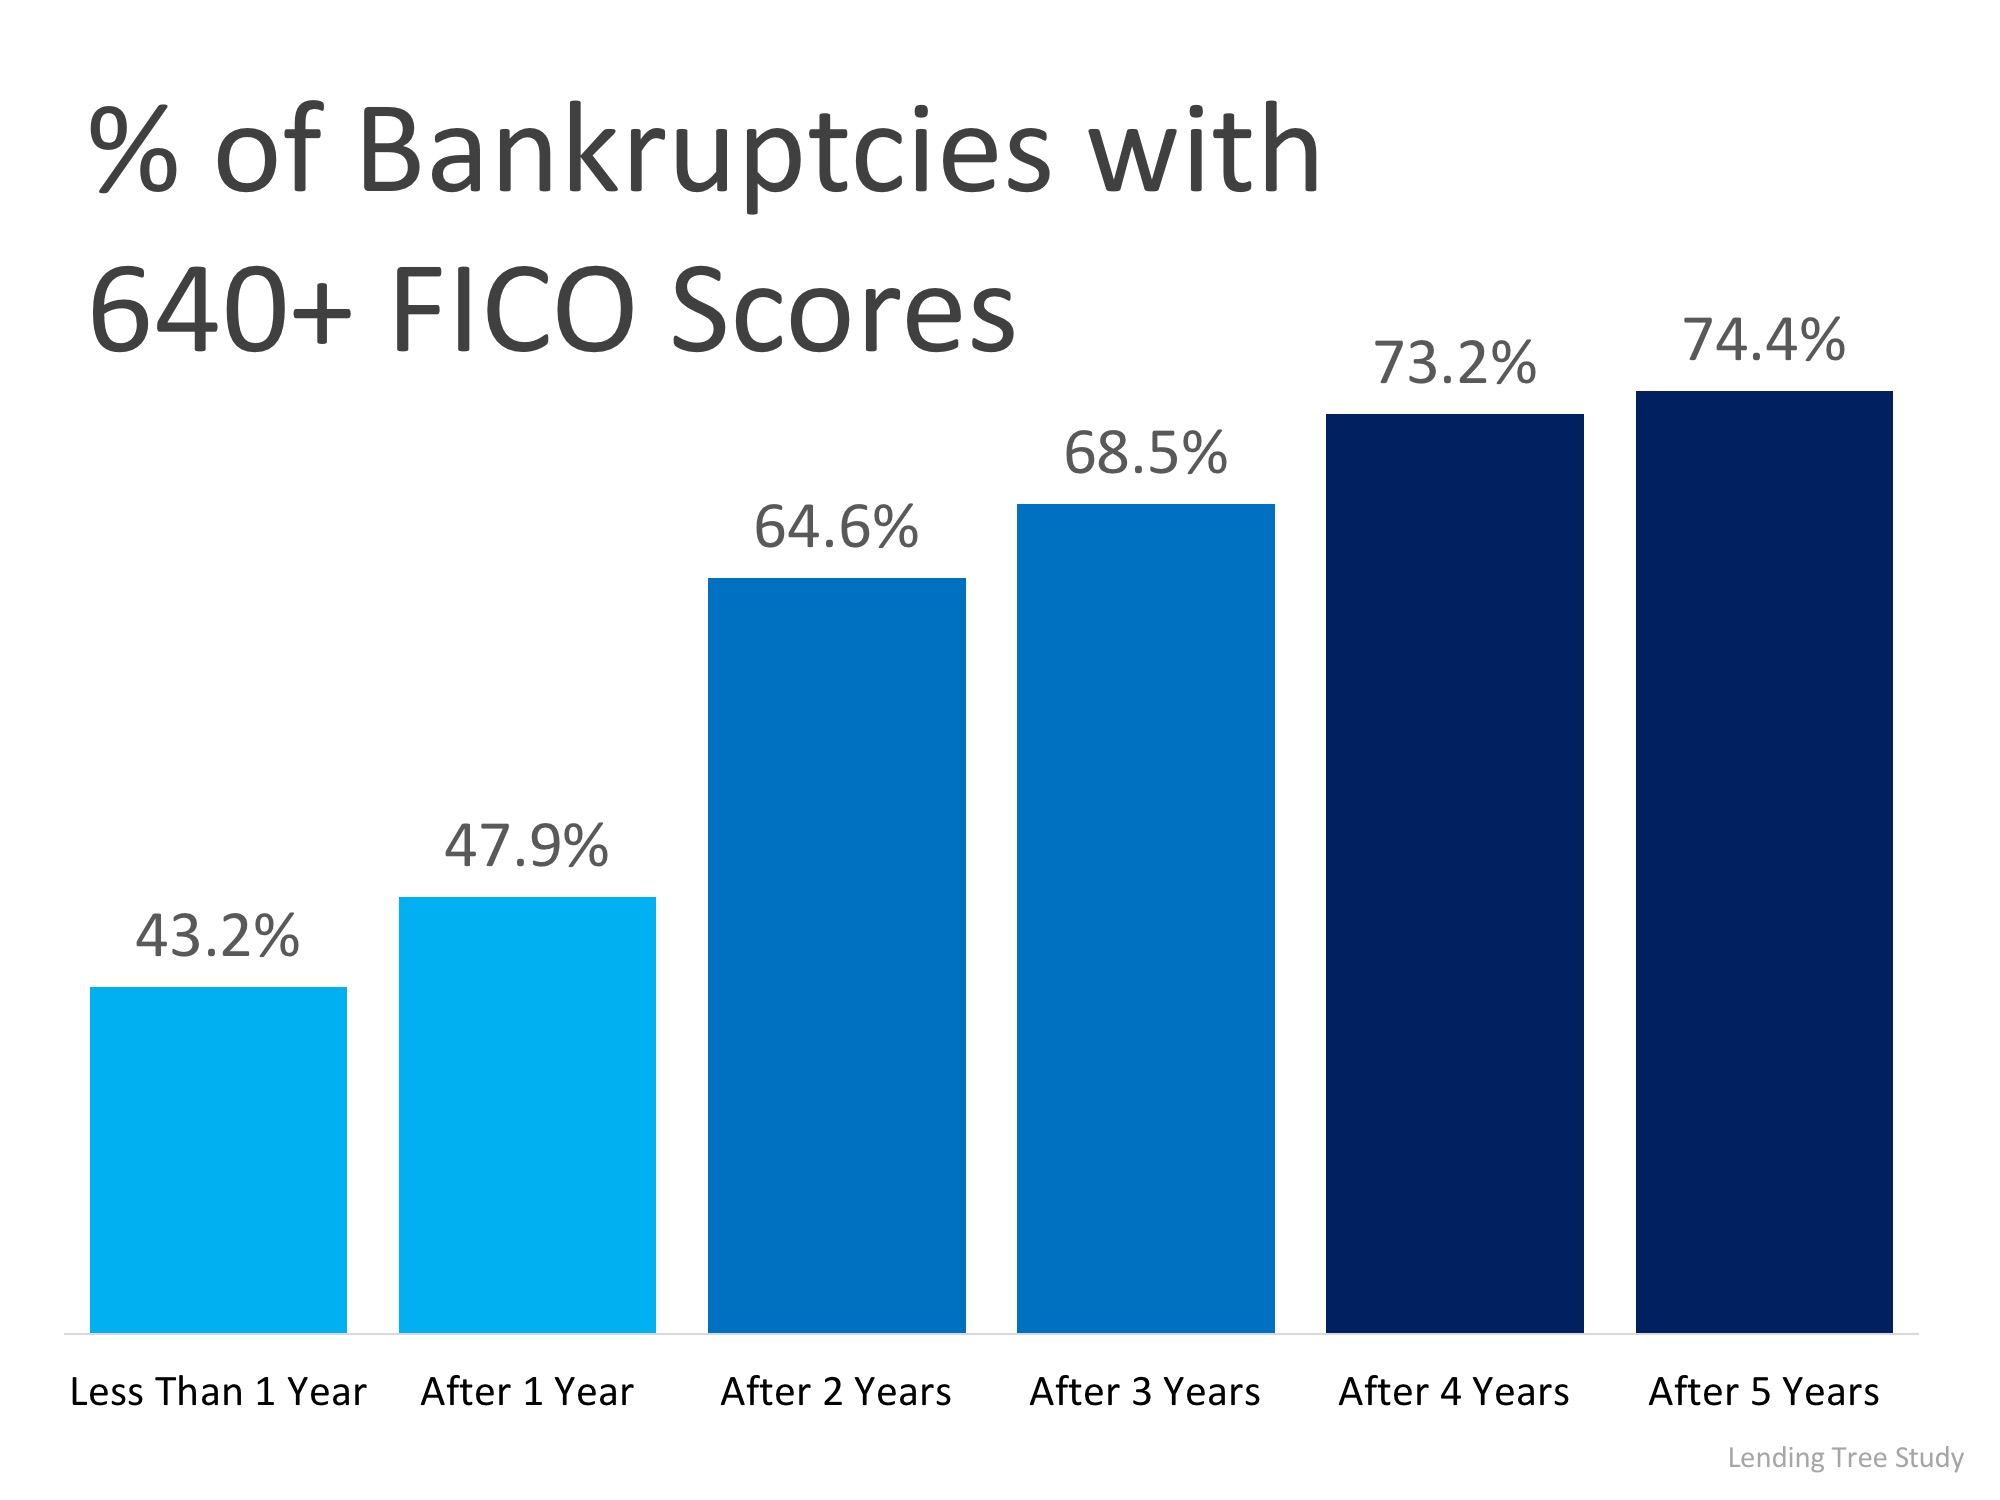
The study found that 43.2% of Americans who filed bankruptcy were able to repair their credit back to a 640 FICO® Score in less than a year. The percentage of those who achieved a 640 FICO® Score increased to nearly 75% after 5 years. The full breakdown of the findings was used to create the chart below.

Boomerang Buyers: Most Qualify for Financing in 2-3 Years | MyKCM

Americans who were able to repair their credit scores to a range of 720-739 within three years of filing were able to obtain the same financing options as those who had never filed bankruptcy.

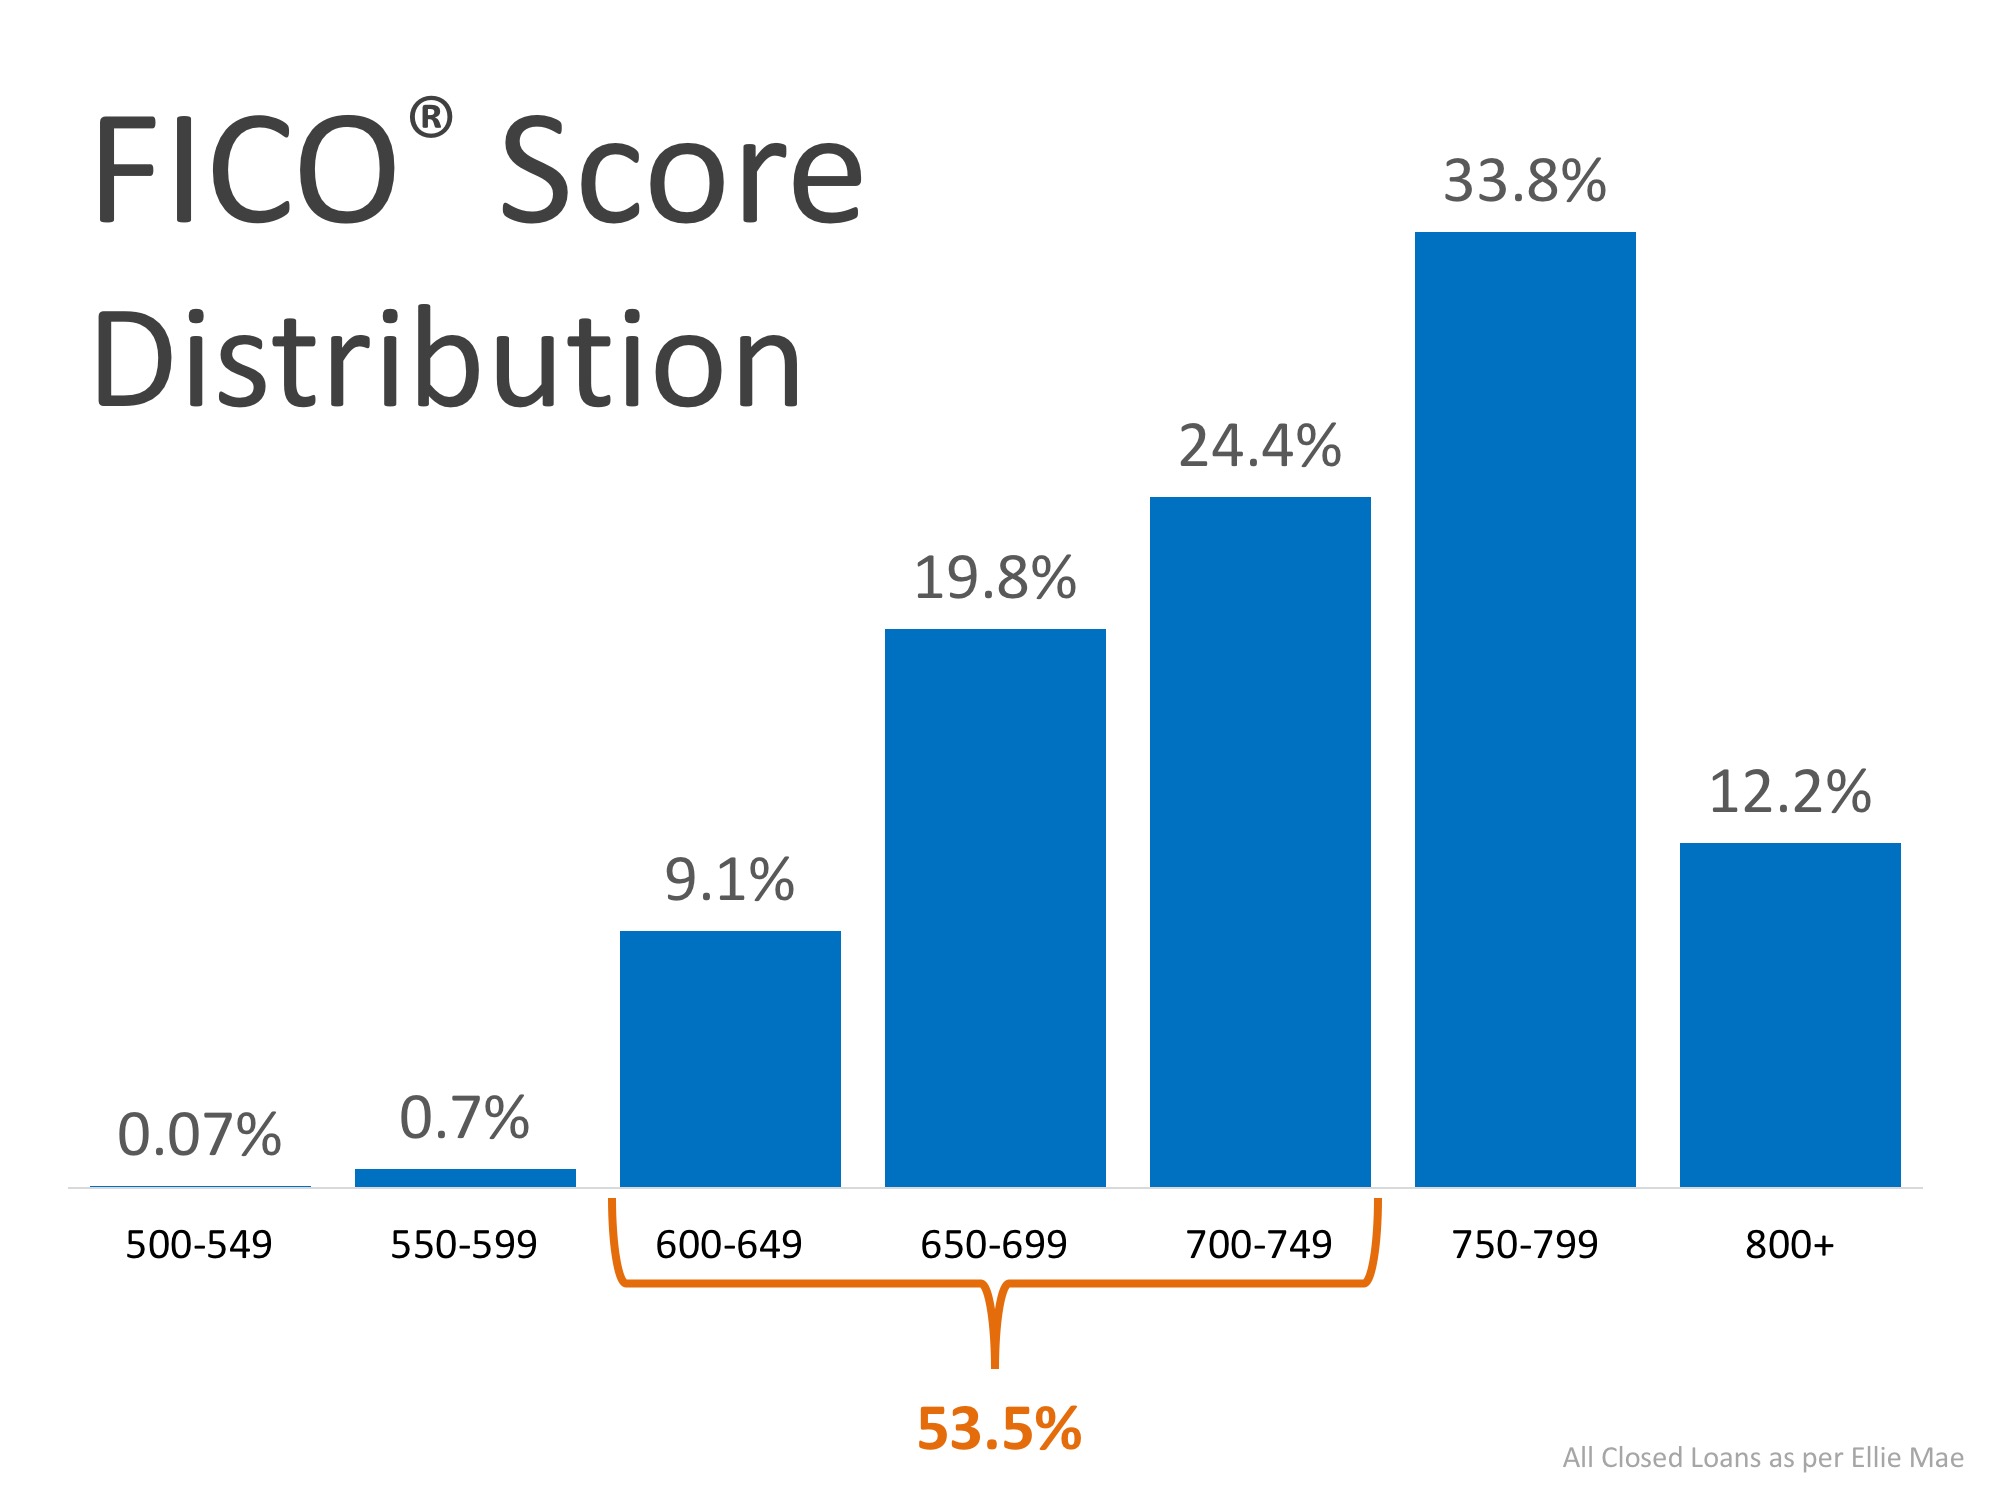
According to Ellie Mae’s latest Origination Insights Report, 53.5% of those who were approved for a home loan had FICO® Scores between 600-749 last month. This is great news for Americans who are looking to re-enter the housing market.

Boomerang Buyers: Most Qualify for Financing in 2-3 Years | MyKCM

Raj Patel, Lending Tree’s Director of Credit Restoration & Debt-Related Services had this to say:

“People may think that filing a bankruptcy would put you out of the loan market for seven to ten years, but this study shows that it is possible to rebuild your credit to a good credit quality.”

“LendingTree’s research found that very few bankruptcy filers have a harder time [obtaining a mortgage] than those who have not filed for bankruptcy.”

Bottom Line

If you are one of the millions of Americans who has filed for bankruptcy and think that you have to wait 7-10 years to make your dream of returning to homeownership a reality, let’s get together to find out if you qualify now.

Posted in Buying a Home